Land Loans for California Property Buyers & Investors
Land loans provide financing for buyers and investors purchasing vacant land, raw land and residential lots.
- Vacant & Raw Land
- Residential Lots
- Property Buyers & Investors
45+ Google Reviews · Santa Cruz
20+ Years
Mortgage Broker Experience
60+ Google Reviews · Carmel
NMLS #279284
Licensed Mortgage Professional
Financing for Your California Land Purchase
Buying land can require a different financing approach than purchasing an existing home. SV Mortgage Group can help review the property, intended use and financing needs to explore land loan options for qualifying California purchases.
-
Vacant & Raw Land
Explore land financing options for qualifying vacant and raw land purchases based on the property, location, intended use and overall transaction.
-
Residential Lots
Lot loans may provide financing for buyers purchasing residential parcels for future use, development or other qualifying real estate plans.
-
Buyers & Real Estate Investors
Whether you're purchasing land for future residential use or as part of an investment strategy, we can review the property and available financing options.
Tell Us About Your Land Purchase
Share a few details about the property, purchase price, intended use and financing needs, and we’ll help you explore land loan options that may fit your purchase.
What Is a Land Loan & How Does It Work?
A land loan is financing used to purchase property that does not have a completed home or other qualifying structure already in place, including vacant land, raw land and residential lots.
Land loans can be structured differently from traditional home mortgages because the property itself, its location, access, intended use and future plans may all affect the financing. Depending on the lender and program, qualification may also consider the purchase price, requested loan amount, borrower financial profile and overall land purchase strategy.
How Land Loans Work
Identify the Property
Start with the vacant land, raw land or residential lot you want to purchase and determine how you intend to use the property.
Review the Land & Purchase
The property, purchase price, location, access, intended use and requested financing may be reviewed to help determine which land loan options could fit the purchase.
Evaluate Land Financing
Available land financing can vary by lender and property type. The borrower profile, requested loan amount and plans for the land may also affect the available structure.
Complete the Land Purchase
If approved, the land loan provides financing toward the qualifying property purchase according to the lender's terms and the structure of the transaction.
Land Loans for Vacant Land, Raw Land & Residential Lots
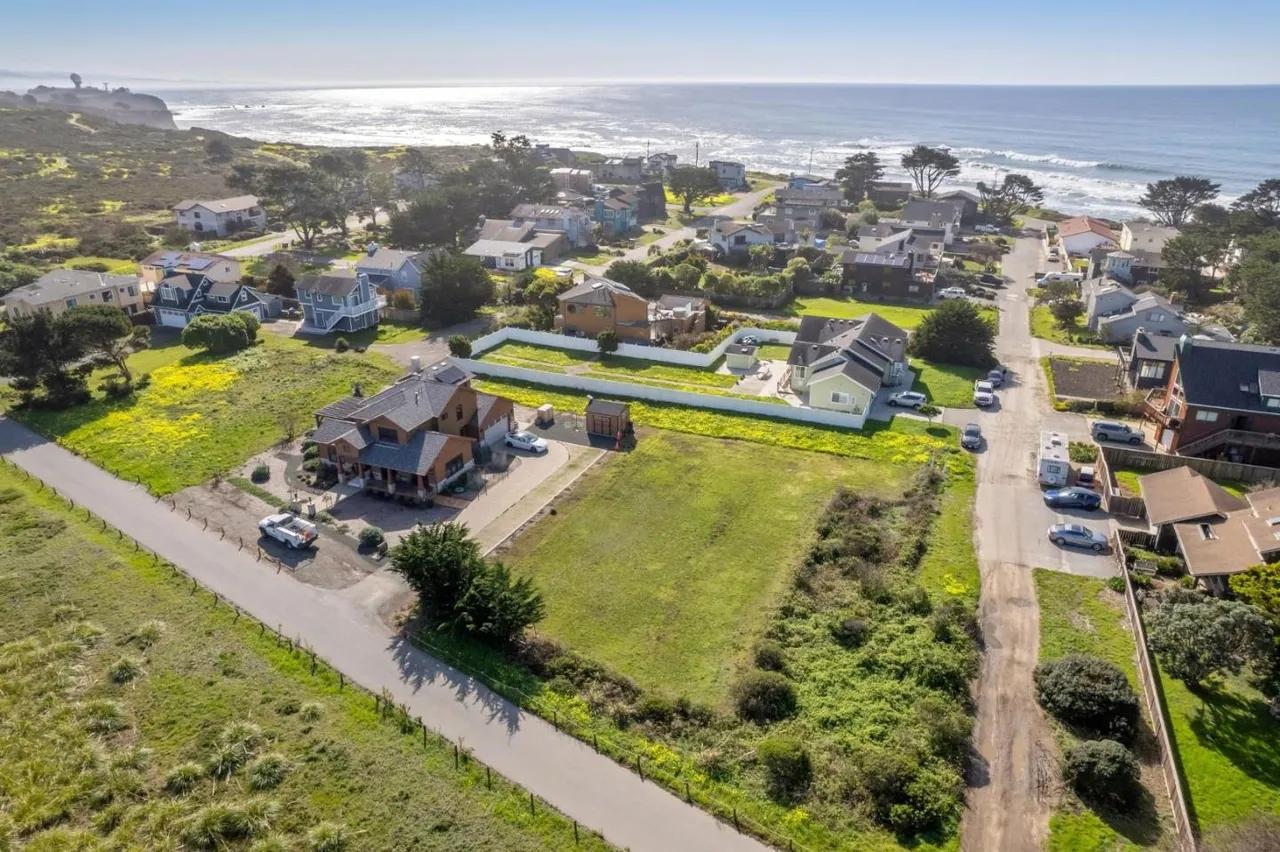
Financing Depends on the Land & Intended Use
Vacant land, raw land and buildable residential lots can present different financing scenarios. Property access, utilities, improvements, location and future plans may all affect which land loan options are available.
Land financing is not one-size-fits-all. A developed residential lot can be different from a vacant parcel or raw land with limited infrastructure. SV Mortgage Group can help review the property, intended use and purchase scenario to explore land loan options that may fit the transaction.
Vacant Land Loans
Vacant land loans can provide financing for qualifying undeveloped parcels being purchased for future residential, investment or other planned real estate uses.
Raw Land Loans
Raw land may have limited utilities, road access or other improvements already in place. These property characteristics and the buyer's future plans can affect how a raw land loan is evaluated.
Residential Lot Loans
Lot loans may provide financing for qualifying residential parcels purchased for a future home, development plan or other intended property use.
Investment Land
Real estate investors may also purchase land as part of a longer-term investment or development strategy. Financing options depend on the property, transaction and intended use.
Land Loan Requirements & How to Qualify
Land loan requirements vary by lender and property, but qualification typically considers the type of land, purchase price, requested financing, borrower financial profile and intended use of the property.
Because financing land can be different from financing a completed home, lenders may evaluate both the borrower and the characteristics of the property. Access, utilities, existing improvements, location and future plans for the land may all affect the available loan structure and qualification requirements.
Qualification Factors
What Land Lenders May Review
Property Type & Location
Whether the property is a residential lot, vacant land or raw land can affect the financing. Location, marketability and surrounding development may also be considered.
Access & Property Improvements
Road access, utilities and other existing improvements can help lenders evaluate how developed the land is and which financing options may fit the property.
Borrower Financial Profile
Credit history, income or financial capacity, liquidity, available funds and reserves may be considered depending on the land lender and loan program.
Down Payment & Available Funds
Land loan down payment requirements vary by lender, property type and financing structure. The borrower's available funds and requested loan amount may affect qualification.
Intended Use & Future Plans
Lenders may want to understand whether the land is being purchased for a future home, investment, development or another qualifying purpose when reviewing the loan.
Land loan requirements vary by lender and property. Property type, access, down payment, credit, liquidity and intended use may all affect qualification.
Land Loan Rates, Down Payments & Terms
Land loan rates, down payment requirements and terms vary by lender, property and financing structure. The type of land, purchase price, property characteristics, borrower profile and intended use can all affect the available financing.
Land Loan Interest Rates
Land loan rates vary by lender and program. Property type, location, access, existing improvements, requested financing and the borrower's financial profile may all influence the interest rate and available loan structure.
Land Loan Down Payments
The down payment needed for a land loan depends on the lender, type of property and overall transaction. Vacant land, raw land and developed residential lots may have different requirements, and borrower liquidity or available funds may also be considered.
Land Loan Terms
Available land loan terms and repayment structures depend on the lender, property and intended use of the land. The financing structure may also differ based on whether the purchase involves a residential lot, vacant parcel, raw land or investment property.
Pricing Factors
What Can Affect Land Loan Rates?
Land Type
Purchase Price
Access & Utilities
Borrower Profile
Loan Structure
Intended Use
Land loan rates, down payment requirements and terms vary by lender and property. SV Mortgage Group can review the land, purchase price, requested financing and intended use to help identify loan options that may fit your purchase.
Financing a Land Purchase
A loan for a land purchase can help buyers and real estate investors finance qualifying property before a home or other planned improvements are in place. The right land financing structure depends on the parcel, purchase details, intended use and plans for the property.
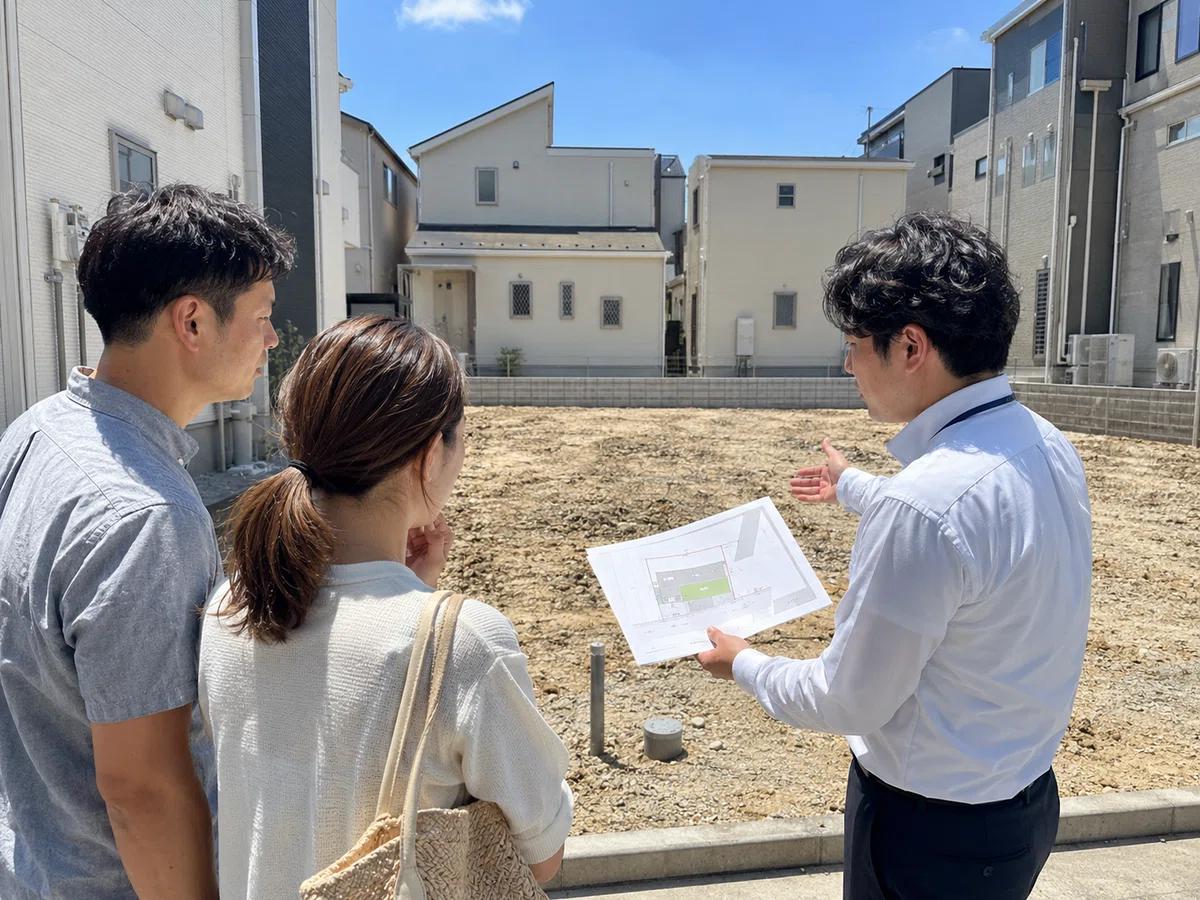
Planning Your Land Purchase
Land Financing for Different Purchase Goals
-
Land for a Future Home
Buyers may use a land purchase loan to acquire a residential lot or qualifying parcel intended for a future home or other residential plans.
-
Buildable Residential Lots
Financing may be available for qualifying buildable lots in established neighborhoods or new developments, with the property and future plans considered as part of the loan review.
-
Investment Land Purchases
Real estate investors may explore land financing when acquiring qualifying property as part of a longer-term investment, development or real estate strategy.
-
Future Property Plans
How you plan to use the land can be an important part of financing the purchase. Future residential or development plans may help determine which land loan options are appropriate for the property.
Land & Construction Financing
If you are buying land with plans to build in the future, financing may involve two distinct stages. The land purchase and future construction can have different requirements, structures and timelines.
Land Acquisition
Financing the Land Purchase
A land loan may finance the acquisition of a qualifying parcel before construction begins. The property, purchase price, borrower profile and intended use may all be considered.
- Vacant land, raw land or residential lots
- Purchase price and requested financing
- Property characteristics and intended use
Future Construction
Planning for Construction Financing
Financing construction may be a separate stage from buying the land. Buyers planning to build should consider how the future project and financing needs relate to the initial purchase.
- Future home or development plans
- Construction timeline and project scope
- Future financing and long-term strategy
Land and construction financing options vary by lender, property and project. Planning both stages early can help you evaluate how the land purchase fits into your broader property strategy.
Land Loans in California
SV Mortgage Group helps property buyers and real estate investors explore land loans in California for qualifying vacant land, raw land and residential lot purchases.
California land loans can differ from financing an existing home because the lender may need to evaluate both the borrower and the characteristics of the property. The type of parcel, access, utilities, existing improvements and intended use may all affect the available financing.
From buildable residential lots in established communities to undeveloped parcels with longer-term plans, each land purchase can present a different financing scenario. SV Mortgage Group can review the property and financing needs to help identify land loan options that may fit the transaction.
Experienced Guidance for Land Financing
Financing land can involve considerations that do not come with purchasing a completed home. The property itself, intended use, financing structure and future plans can all influence which loan options may be available.
With more than 20 years of mortgage broker experience, Shane Valente helps California property buyers and real estate investors evaluate land financing scenarios, compare available options and identify a financing approach that may fit the property and purchase plan.
Common Questions About Land Loans
Land loan requirements, down payments, rates and terms can vary based on the lender, borrower and property. Here are answers to common questions about financing vacant land, raw land and residential lots.
A land loan is financing used to purchase property that does not have a completed home or other qualifying structure already in place. Depending on the lender and property, land loans may be used to finance vacant land, raw land or a residential lot intended for future use.
A land lender typically evaluates both the borrower and the property being purchased. The review may include the purchase price, requested loan amount, property type, location, access, utilities, existing improvements, borrower financial profile and intended use of the land. If approved, the loan provides financing toward the land purchase according to the lender's terms.
To get a loan for land, you generally need information about the property and your financing request. This may include the purchase price, property details, intended use, requested loan amount and information about your financial profile. A mortgage broker can review the scenario and help identify land financing options that may fit the purchase.
Land loan requirements vary by lender, property and loan structure. Lenders may review the type and location of the land, road access, utilities or improvements, purchase price, down payment, borrower credit and financial profile, available funds and the intended use of the property.
There is no single down-payment requirement for every land loan. The amount required can depend on the lender, type of land, purchase price, requested financing, property characteristics and borrower profile. Raw or less-developed land may be evaluated differently from a buildable residential lot with access and utilities already available.
Land loan rates and terms vary by lender and transaction. Pricing and loan structure may be influenced by the property type, location, purchase price, requested loan amount, borrower profile, down payment and intended use of the land. Current options should be reviewed for the specific property rather than assuming one standard rate or term applies to every land purchase.
Financing may be available for qualifying vacant land and raw land, but lender requirements can differ based on how developed the property is. Access, utilities, existing improvements, location and the buyer's plans for the property may all be considered when determining which land loan options are available.
Credit requirements vary by land lender and loan program. Some financing options may consider additional factors such as the property, down payment, available funds and overall borrower profile alongside credit history. Lower credit can limit available options or affect loan terms, so the complete property and borrower scenario should be reviewed.
SV Mortgage Group can review your land purchase and financial profile to help determine which financing options may be available for the property.
Ready to Discuss Your Land Purchase?
Tell us about the property, purchase price, intended use, financing needs and future plans. We can review your scenario and help identify land loan options that may fit the property and your purchase goals.